Meal delivery tax deduction in France: deduction, relief or credit?
The meal delivery tax deduction in France is the question raised by households who receive meals at home and wonder whether the cost can be subtracted from what they owe. In French tax law the word deduction has a precise meaning: an amount taken off taxable income before the tax is calculated. For this kind of spending, however, the usual mechanism is not a deduction but a tax credit, which is set against the tax itself.
The difference is more than vocabulary. A deduction lowers the taxable base, so its value depends on the taxpayer’s tax band. A credit produces a defined benefit, even for a household that pays no income tax, which can then receive a refund. Personal services follow this second logic.
A useful rule of reading follows. When a provider or an article speaks of a deduction for delivered meals, check whether it really means the personal-services tax credit. The two expressions are mixed up in everyday speech, although the calculations differ.
Tax relief on delivered meals: what the credit accepts and leaves out
In practice, tax deduction for delivered meals runs through the credit for personal services, which is 50% of eligible spending in the year, with a ceiling. As an example, the general ceiling is 12,000 € a year, higher in some family situations. For 2026 spending, the tax administration states that home meal delivery qualifies even when it is not part of a wider package of services.
What counts is the service invoiced by an organisation working at the home, or the pay of an employee hired directly. What does not count: the price of the food itself when it is not built into the service, anything paid in cash, and amounts already covered by an aid such as the APA, which is subtracted from the base.
A taxpayer who already deducts maintenance payments made to an elderly parent cannot also use the credit for that same parent. This incompatibility is among the most often forgotten in families supporting a relative.
Delivered meals or cooking at home: two distinct tax situations
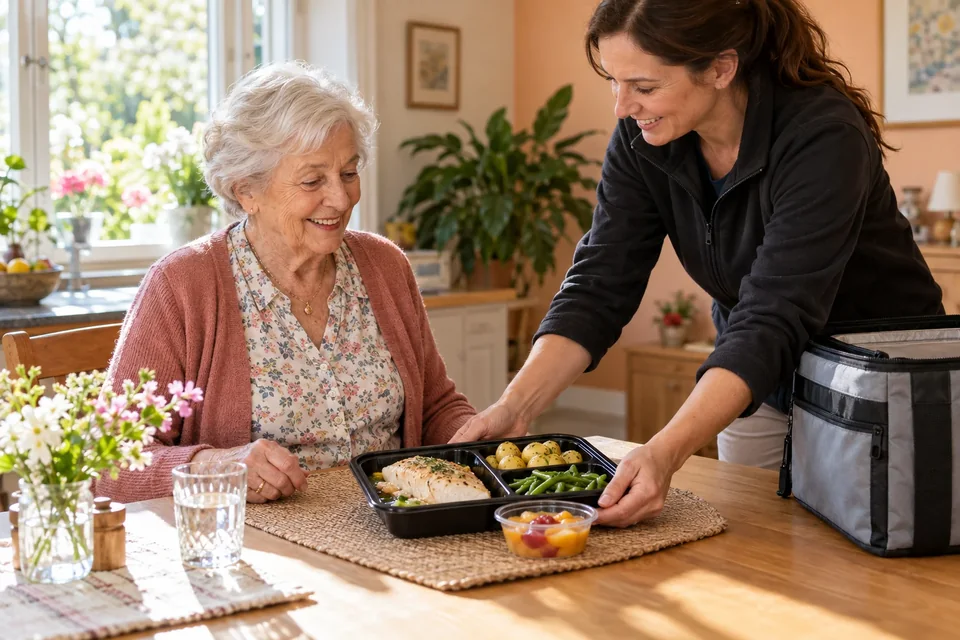
For the meal delivery tax deduction in France, the starting point is that delivery brings dishes cooked elsewhere, in a central kitchen or by a caterer. Cooking at home means a worker prepares food in the person’s own kitchen. Both belong to the world of personal services, but the supporting papers differ.
- Meals delivered by an organisation: the invoice shows the price of the meals and, depending on the case, delivery charges. You need to know what the provider includes in the eligible service.
- Cooking at home by an employee: hours worked are the proof, with certificates produced from the declaration of the employment.
- Groceries delivered without cooking: the position depends on how the provider is organised, so ask for an itemised invoice.
If one provider invoices both meals and help getting up in the morning, ask for separate lines. A clear document simplifies the return and any later check.
Tax credit for meals at home: who can claim
The tax credit for meals at home requires a tax home in France and a service carried out in France, either at the taxpayer’s home or at that of a parent who receives the APA. The latter option matters to many adult children who finance a parent’s meals: under conditions, they can declare the expenses they bear for that parent.
Next, the provider must be able to issue proper invoices. A charity, a personal-services company or a municipal service can do so; an informal delivery paid hand to hand leaves no usable trace.
Finally, for a tax deduction for delivered meals, look at the nature of the service. A meal ordered online from a general platform that delivers a restaurant’s food is not a home-help service: the tax benefit targets personal services, not everyday consumption. The line can seem thin, so when in doubt ask the provider whether it falls within personal services and on what basis.
A simple worked example, for illustration only
In a meal delivery tax relief calculation, take an illustrative case with no scale value. An older person receives delivered meals whose yearly invoice for eligible services is 2,000 €. If no aid is subtracted and the ceiling is not reached, the credit is half of that amount, 1,000 €.
Now suppose the APA covers 600 € of the same invoice. The base falls to 1,400 € and the credit drops to 700 €. The logic is identical for other aid: first remove what has been refunded or paid by someone else, then apply the rate.
These figures do not promise a guaranteed benefit. They only show the mechanism. The real amount depends on the expenses retained, the ceiling that applies to the household and any aid received.
Keeping proof: invoices, payments and advances
To support a meal delivery tax deduction in France claim, keep the organisation’s invoices or the certificates linked to direct employment, plus proof of payment by any means other than cash. They are not attached to the return, but the administration may ask to see them during the checking period.
File them by year in a dedicated folder, with a monthly table of what was paid and what was refunded. If several sources fund the meals, note who paid each part.
An advance of 60% of the credit is paid in January to taxpayers who benefited the previous year, and the balance is worked out in the summer once the new return is processed. The advance is adjusted or repaid according to real spending.
Mistakes in a meal delivery tax deduction claim
These are the slips that most often spoil a claim for meal delivery tax relief.
The commonest is declaring the full cost of the meals, aid included. The tax office soon spots the gap with the data sent by providers, and putting it right is unpleasant.
The second is mixing up invoices for food purchases with an invoice for a service. The third is forgetting an aid paid late in the year. The fourth is declaring meals eaten outside the home, for instance in a seniors’ lunch club, as though they were a home service.
Before completing the return, reread the official guidance for the year: rules change, notably for services supplied outside the home and for the immediate-advance arrangement.
When to ask a professional
If the situation mixes several aids, a parent living with you, maintenance payments or an employee at home, an appointment with the local tax office or a wealth adviser clarifies the choices. Most tax offices answer precise questions provided you arrive with the invoices in hand.
For isolated older people, a social worker at the town’s social action centre or the pension fund can help build the file. Nobody is obliged to cope alone, and support avoids months of letters with the administration.
Frequently asked questions
Can I deduct meal delivery from my income in France?
Not as a deduction from income in the strict sense. It may give a 50% tax credit on eligible spending under the personal-services rules, subject to conditions and a ceiling.
Can a household that pays no income tax benefit?
Yes. A credit can be refunded when it exceeds the tax due, which is what separates it from a simple tax reduction.
Can I claim for meals delivered to a parent?
It is possible when the parent receives the APA and the legal conditions are met. The expenses cannot be combined with deducting maintenance payments for the same parent.
Which documents should I keep?
Provider invoices, certificates for direct employment and proof of payment other than cash. They are shown on request, not attached to the return.